 Digital Onboarding
 AML
 Credit Analysis
 Card Issuance
 Payment Dispersion
 Notifications
 Collections
 Bill Payment
 Alternative Scoring
 Device Lock

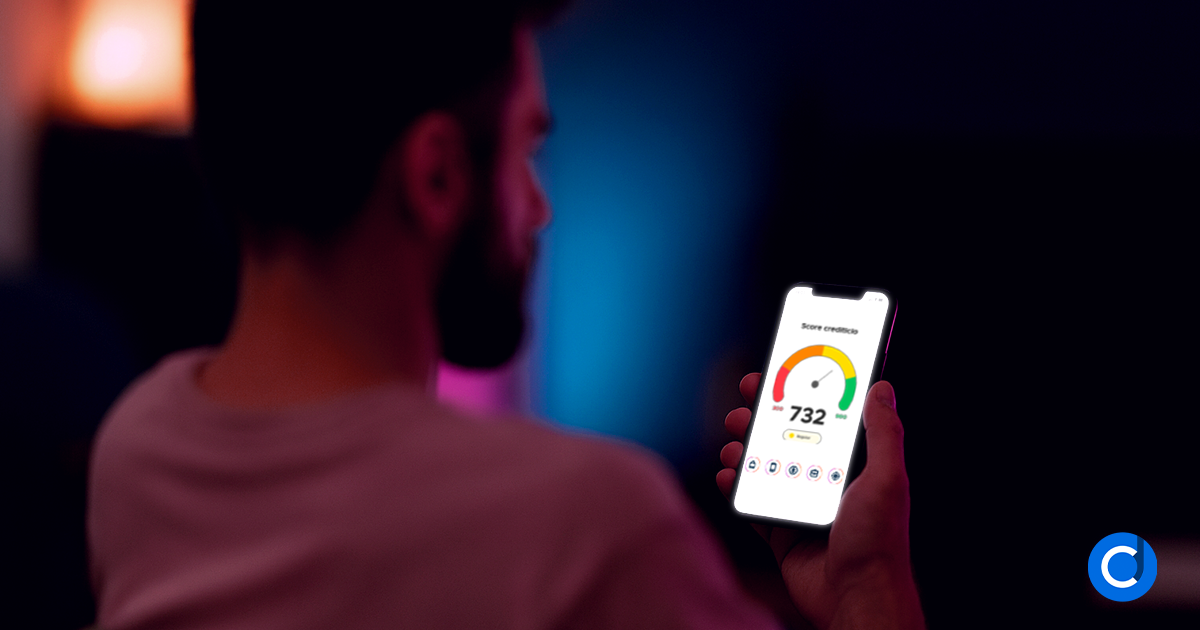
Many people and small businesses have limited traditional credit histories despite having stable financial behavior. Alternative credit scoring can add relevant signals to help lenders evaluate these applicants more completely.
What alternative scoring uses
Depending on consent, purpose, and applicable law, models may analyze cash-flow patterns, payment behavior, business activity, application consistency, and selected digital signals.
Benefits
- Evaluate thin-file customers
- Improve segmentation
- Reduce uncertainty with additional evidence
- Automate decisions through APIs
- Expand responsible access to credit
It should complement, not blindly replace
Alternative models are often strongest when combined with traditional information, affordability analysis, policy rules, and specialist review for exceptions.
Responsible use
Institutions should establish consent, privacy safeguards, data quality controls, explainability, fairness testing, model validation, drift monitoring, and human accountability.
Integration with the credit process
Connecting scoring with onboarding, decisioning, the financial core, and portfolio performance allows the model to be measured and improved.
Dynamicore integrates alternative credit scoring into digital credit workflows.